

Critical illness versus income protection: What do you really need?
3rd November 2026
When you’re building a comprehensive financial plan, you may naturally think of life insurance as the best way to protect your family if the worst happens.
Whilst life insurance is vital for protecting your family after you pass, the reality is that you are more likely to need critical illness cover or income protection during your working years than you are to pass away prematurely.
Indeed, data from the
This is where “living policies” – insurance designed to support you whilst you’re still alive – come into play. The two primary types in the UK are critical illness cover and income protection.
Because both types of protection shield your family from financial difficulties due to poor health or injury, they are often confused. However, they operate in fundamentally different ways and address unique financial risks.
Understanding how each policy works means you can build a financial plan that genuinely fits your household’s needs.
Critical illness cover pays a tax-free lump sum upon the diagnosis of a specified condition
Critical illness cover is designed to deliver a single, tax-free lump sum payout if you are diagnosed with a medical condition listed in your policy documents.
Subject to conditions in the policy, common conditions could include, , but are not limited to:
- Cancer
- Heart attacks
- Strokes
- Major organ transplants
- Multiple sclerosis
Once a claim has been approved and the lump sum paid out, the policy usually terminates.
When a critical illness payout could work best:
- Clearing debt. Using the lump sum to pay off part of your mortgage or clear outstanding debts can help reduce or remove your largest monthly expense during your recovery.
- Funding home adaptations or private care. You may need to cover immediate, large financial outlays, such as modifying your home for accessibility, buying specialised equipment, or funding private medical treatment.
- Providing a financial cushion for lifestyle changes. Giving your family a dedicated lump sum to adjust your lifestyle, such as reducing working hours or allowing a partner to take unpaid leave, could make it easier to receive care and support for recovery.
Whilst a tax-free lump sum provides valuable immediate capital, critical illness cover does not replace your ongoing, regular monthly income over a prolonged period.
This is where income protection can be useful.
Income protection provides an ongoing monthly income if you are unable to work due to illness or injury
Unlike the single payout of critical illness cover, income protection acts as a replacement for your regular monthly salary. If an illness, injury, or specified mental health condition prevents you from working, an income protection policy pays out a tax-free monthly income until you recover, return to work, reach retirement age, or pass away.
Policies will typically cover a percentage of your gross pre-injury or illness earnings. This is something you would predetermine, as well as selecting a deferment period.
The deferment period is the waiting time between when you stop working and receive your first payment. This can be anywhere from 4 to 52 weeks, allowing you to tailor your cover to any employee benefits or emergency cash savings you already have.
When income protection could work best:
- Meeting ongoing household commitments. Income protection could support you by providing a predictable monthly cash flow to pay your rent or mortgage, utility bills, food, and other everyday living expenses.
- Covering a wider range of conditions. Critical illness policies can have strict criteria, so having income protection could protect you against conditions that cause prolonged absences from work but may not meet the criteria of a critical illness.
- Supporting long-term recovery. Sustaining your family’s standard of living may not be possible with a lump sum, but regular payments could help support you if your illness or injury permanently restricts your ability to work.
Because income protection pays out continuously for as long as you are medically unfit to work, it provides protection for your ongoing financial plan and ability to earn an income.
Comparing the differences in protection plans could highlight why both may be necessary
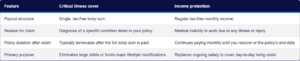
Choosing between two types of protection comes down to identifying which financial vulnerability would cause the most disruption to your household.
The table below outlines the core practical differences between critical illness cover and income protection:
Combining different plans often creates the most robust financial safety net
Because critical illness cover and income protection address very different aspects of financial risk, choosing one over the other could leave a gap in your shield.
For example, relying solely on critical illness cover means you would not receive a payout if a severe back injury kept you out of work for more than a year, as this does not meet the definition of a critical illness.
In the same vein, if you were relying on income protection as your only means of support, then you may lack the capital sum required to pay off your mortgage or fund specialist home adaptations.
Combining both policies means you can establish a dual-layer safety net. When combined with life insurance, you have a financial safety net that covers you both in life and death.
Working out the right balance for your unique needs is where we come in.
Get in touch
Finding out the right balance between critical illness cover, income protection, and life insurance depends on your occupation, employer benefits, existing liabilities, and your family budget.
We can help you navigate this and ensure you are fully protected, no matter what life throws your way.
Email us at enquiries@pen-life.co.uk, or call 01904 661140 to learn more.
Please note
This article is for general information only and does not constitute advice. The information is aimed at individuals only.
All information is correct at the time of writing and is subject to change in the future.
Note that life insurance and financial protection plans typically have no cash in value at any time and cover will cease at the end of the term. If premiums stop, then cover will lapse.
Cover is subject to terms and conditions and may have exclusions. Definitions of illnesses vary from product provider and will be explained within the policy documentation.
Category: Protection
